
HKMA Stablecoin Licence vs TCSP: 2025 Compliance Guide

HKMA Stablecoin Licence vs TCSP: 2025 Compliance Guide
If you’re planning a fiat-backed stablecoin in Hong Kong, the question I hear most is: do we really need an HKMA licence, or can a TCSP licence cover us? As of 1 August 2025, the answer is clear—issuance of fiat-referenced stablecoins is a regulated activity under the Stablecoins Ordinance, and you need the HKMA’s licence. A TCSP licence won’t substitute it.
That clarity is new, and it changes launch plans, distribution, and timelines.
What changed in 2025
- The Stablecoins Ordinance took effect on 1 August 2025. Issuing fiat-referenced stablecoins in or from Hong Kong now requires an HKMA licence. See HKMA’s supervisory materials: https://www.hkma.gov.hk.
- On 26 May 2025, the HKMA consulted on detailed AML/CFT requirements for licensees. Expect full-scope CDD, ongoing monitoring, and governance expectations tailored to stablecoin risks.
- OTC distribution is narrowing: under the Government’s OTC consultation, licensed VA OTC operators serving retail may only deal in (i) virtual assets admitted for trading on at least one SFC-licensed VATP and (ii) stablecoins issued by HKMA-licensed issuers. This signals that unlicensed stablecoins won’t have compliant retail distribution via OTCs. See the SFC VATP regime: https://www.sfc.hk/en/Regulatory-functions/Intermediaries/Virtual-asset-trading-platforms.
HKMA licence vs TCSP: the real differences
| Topic | HKMA Stablecoin Issuer Licence | TCSP Licence (Hong Kong) |
|---|---|---|
| Regulator | Hong Kong Monetary Authority | Companies Registry |
| What it covers | Issuing fiat-referenced stablecoins; reserves, governance, issuance/redemption, disclosures, AML/CFT | Company formation, directorship/secretary, trust/company services under AMLO |
| Can it replace the other? | No (different from TCSP scope) | No (cannot cover stablecoin issuance) |
| Reserves/custody | Expect 1:1 fiat-referenced reserves and segregation; proposed exemption from separate VA custodian licensing if you only custody your own stablecoin for clients | No prudential reserve or wallet requirements |
| Distribution | You may use third-party distributors; HKMA views them as your customers—full AML/CFT duties apply to them | Not relevant |
| Retail access via OTC | OTCs may deal in your coin only once you’re HKMA-licensed (per OTC consultation) | Not relevant |
| When TCSP still helps | Not applicable | Useful for SPVs, trustees, directors/company secretary for reserve vehicles—but this is ancillary, not a substitute |
Two subtleties matter:
- Third-party distribution: The HKMA has stated that where licensees use third-party entities to distribute their stablecoin, those entities are customers of the licensee. Build onboarding, contractual oversight, and ongoing monitoring around that fact.
- Custody overlap: If you only custody your own stablecoin for clients, the Government has proposed exempting you from a separate VA custodian licence because the HKMA already supervises you.
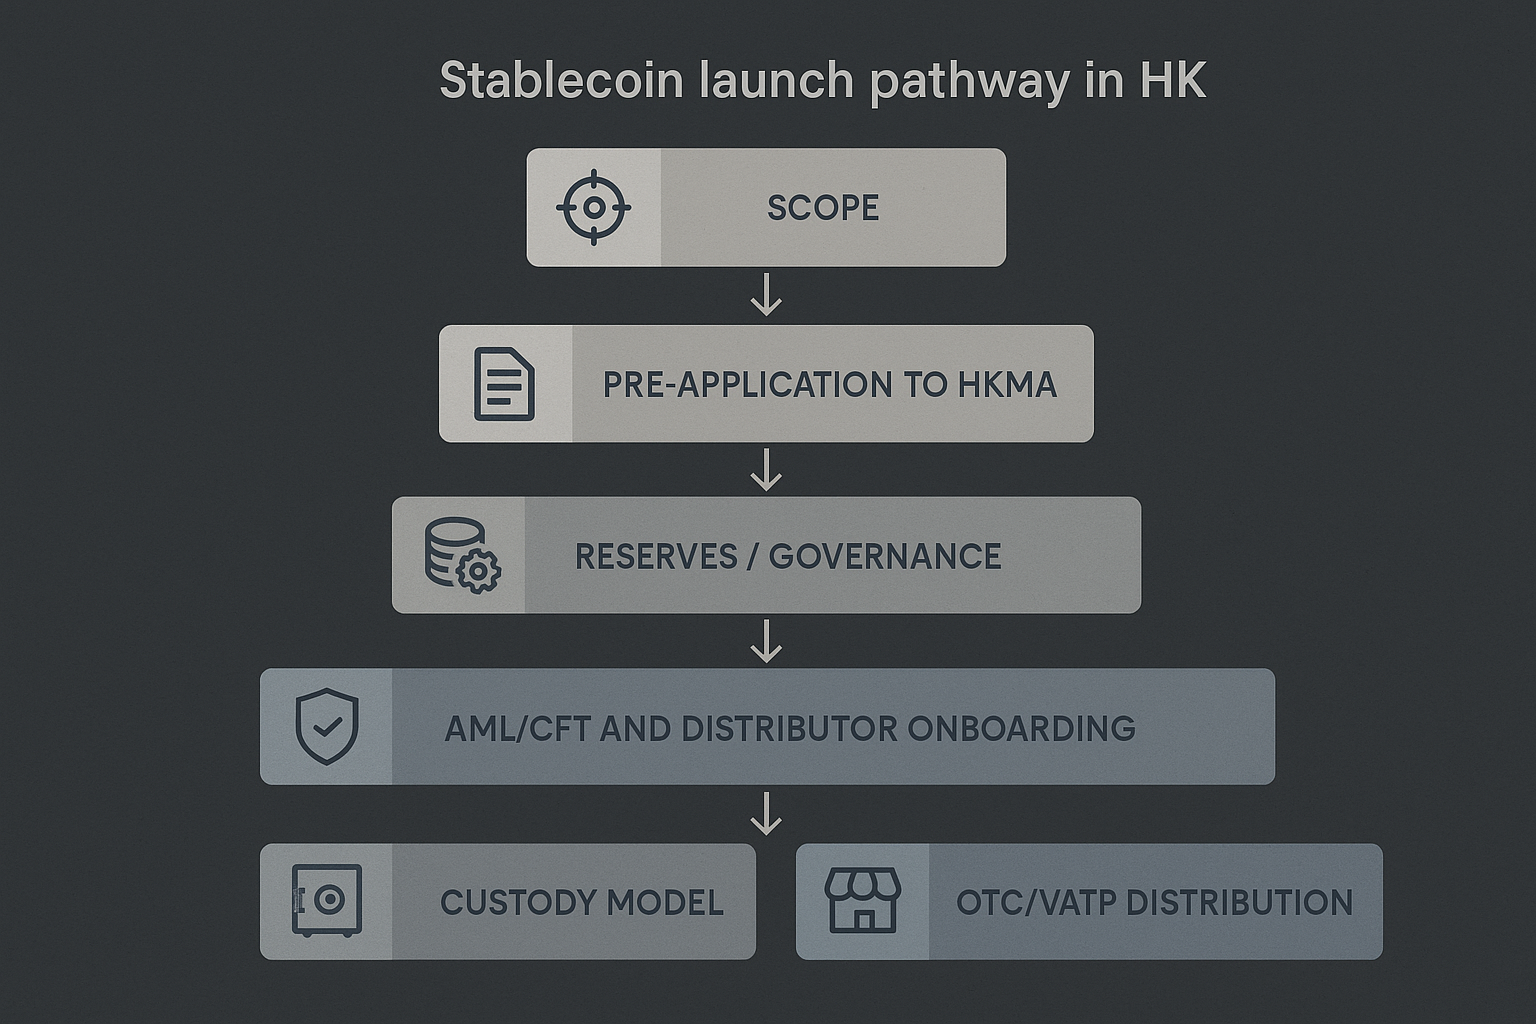
What to do now (practical path)
-
Scope check
- Are you issuing or actively marketing a fiat-backed coin to Hong Kong? You’re in HKMA territory.
- If you only need an SPV/trust to hold reserves, a TCSP can support corporate/trust administration—but you still need the HKMA licence to issue.
-
Engage early with the HKMA
- Book a pre-application meeting. Bring your product map, reserve model, audit plan, redemption mechanics, and AML programme (including how you treat distributors as customers).
-
Design reserves and disclosures
- Define eligible reserve assets, segregation, and reconciliation. Daily backing and monthly attestations are increasingly expected in market practice (illustrative).
-
Build AML/CFT for distribution
- Map all distribution channels (VATPs, OTCs, wallets, merchants). For each, apply risk-based CDD, sanctions screening, and transaction monitoring consistent with the HKMA’s May 2025 AML consultation.
-
Plan retail access
- To reach Hong Kong retail via OTC, your coin must be HKMA-licensed. For exchange listings, target SFC-licensed VATPs; products accessible to retail are limited under SFC rules.
-
Architect custody
- If you hold only your own stablecoin keys for clients, leverage the proposed custodian exemption. Otherwise, expect a separate VA custodian licence once finalised.
Bottom line
A TCSP licence helps you stand up entities and trusts. It won’t let you issue a stablecoin. For fiat-backed issuance in Hong Kong, plan around the HKMA licence, design for third‑party distribution as “customer” relationships, and align with the SFC/VATP and OTC perimeter from day one.
If you want a quick scoping review, we can tell you in one hour whether your target model needs: (i) HKMA issuer only, (ii) issuer + custodian planning, and/or (iii) ancillary TCSP support.


