
HK Compliance: SOW for RWA Tokenisation & CRA Rules

HK’s tokenisation push is real. Policy Statement 2.0 explicitly calls for incentivising tokenised RWAs and stablecoin-based payment use cases, while HKMA’s Project Ensemble (with SFC co-leading the asset management workstream) is piloting tokenised funds and revenue-stream RWAs. But two compliance pillars will decide whether your launch gets banked and can scale: Source of Wealth, and the OECD’s Crypto-Asset Reporting Framework (often called “CRA rules”, formally CARF).
What Hong Kong is encouraging—within guardrails
- Tokenised funds, money market funds, and RWA revenue streams are “in-scope” innovation under Policy Statement 2.0.
- VA custodians—licensed or registered—must meet AMLO Schedule 2 CDD and record-keeping requirements. This is not negotiable and will apply equally to RWA token arrangements involving custodial wallets.
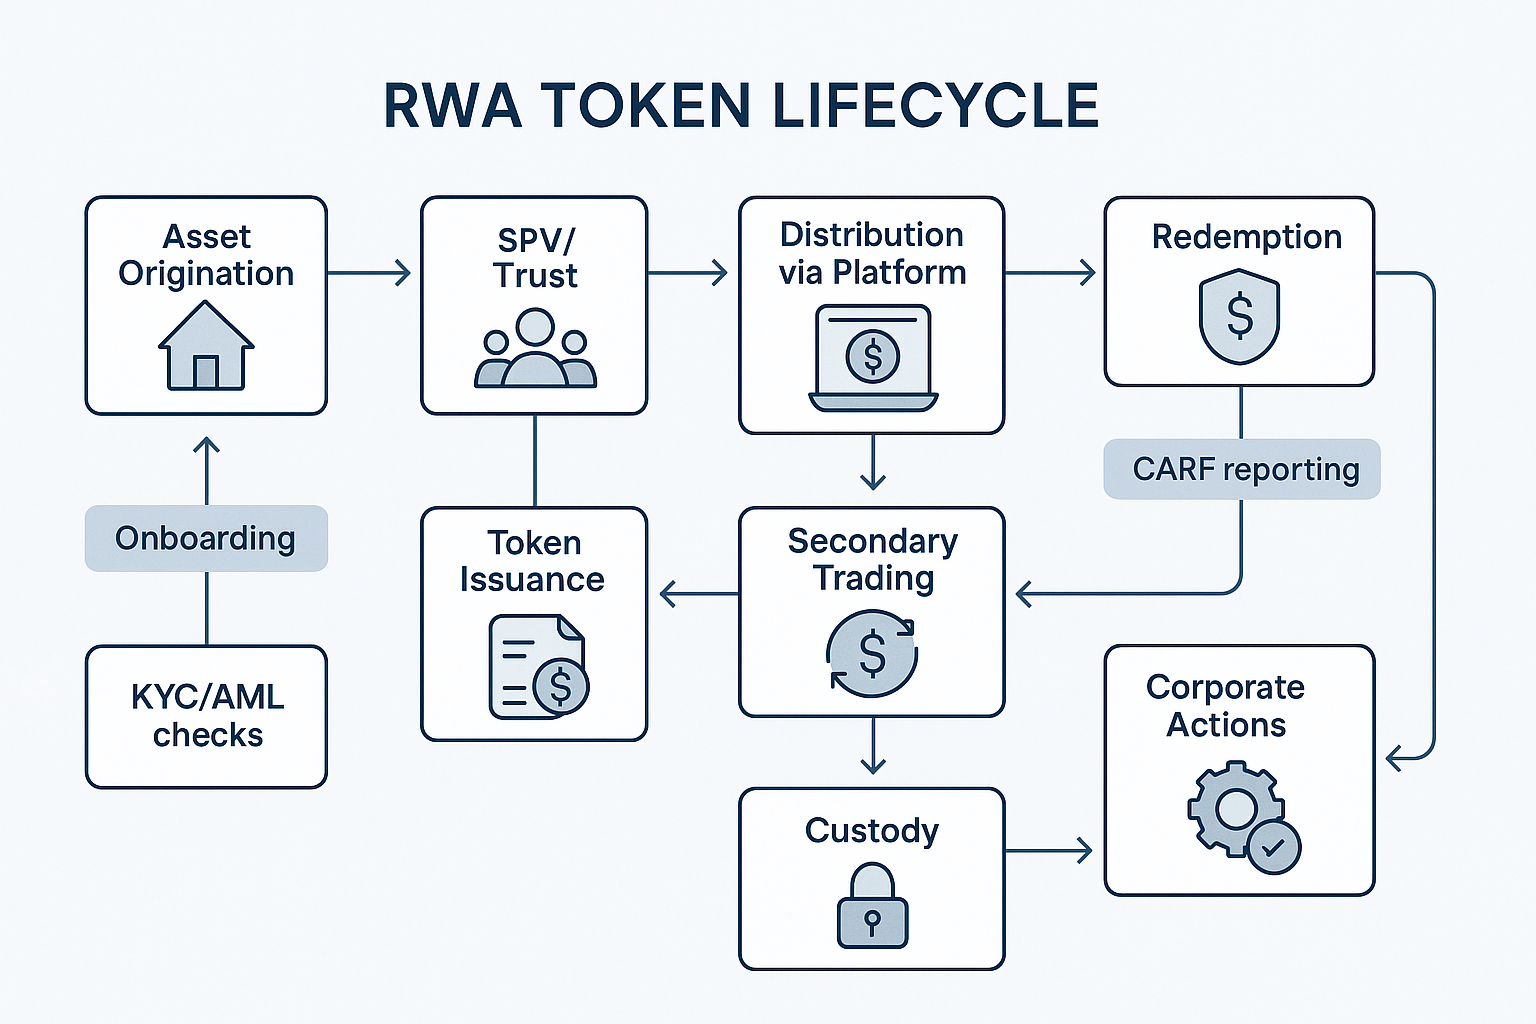
Source of Wealth for RWA tokenisation: what “good” looks like For RWA issuers, platforms, and custodians, SOW must be risk-based, asset-specific, and wallet-aware. Treat it like a capital formation narrative, supported by third-party evidence.
- Map the legal/economic chain: ultimate owner → issuer/SPV/trust → token holders → designated wallets. Use a control matrix and require wallet attestation (including non-custodial).
- Tie fiat and on-chain flows: require verifiable funding trails for primary subscriptions and redemptions; implement Travel Rule messaging for transfers between VASPs.
- Escalate for higher-risk RWAs (private credit, single-asset real estate, exotic revenue streams).
Typical SOW evidence that passes HK scrutiny
| Declared wealth source | Evidence that tends to pass | Red flags that trigger EDD |
|---|---|---|
| Business proceeds | Audited financials, tax returns, dividend statements | Shell companies with no payroll/operations |
| Employment income | Employment contracts, payslips, MPF/IR tax filings | Cash-only income, unverifiable employers |
| Property sale | Sale & purchase agreements, land registry extracts, bank remittance | Complex nominee chains, rapid flip cycles |
| Investment gains (securities) | Broker statements, custodian confirmations | Thinly-traded penny stocks, wash-trading patterns |
| Crypto gains | Exchange histories, on-chain proofs, tax filings where applicable | Mixers/tumblers use without rationale |
| Inheritance/gifts | Probate/wills, notarised deeds, donor SOW | Donor from sanctioned/high-risk jurisdiction |
Key doc retention: minimum 5–7 years depending on the record type and your licence category under AMLO Schedule 2; align policies with custodian obligations proposed for VA custodians.
OECD “CRA” rules in practice: CARF readiness for tokenised RWAs Policy Statement 2.0 flags adoption of the Crypto-Asset Reporting Framework for tax transparency. Expect Hong Kong to align reporting from platforms, exchanges, and certain custodians that intermediate crypto-assets—including tokenised RWAs.
What this means:
- Who reports: “Reporting crypto-asset service providers” (RCASPs) that effect exchanges or transfers for customers—RWA issuance/market platforms are likely in-scope if they facilitate customer transactions.
- What is reported: customer identity, jurisdiction(s) of tax residence, transaction values, and crypto-asset identifiers across on/off-ramp events.
- Overlap with CRS: CARF covers crypto-assets; CRS covers financial accounts. Tokenised fund units may be caught by both depending on structure.
Quick contrast
| Item | CRS | CARF (“CRA”) |
|---|---|---|
| Scope | Financial accounts | Crypto-asset transactions |
| Reporter | FIs (banks, custodians, funds) | RCASPs (exchanges, broker-like platforms, some custodians) |
| Data | Balances, income | Transfers, exchanges, gross proceeds |
| Start | Already live in HK | HK has signalled adoption; plan for 2026 tax year as a prudent assumption (illustrative) |
What to do now (90-day plan)
- Build a SOW playbook per asset class; pre-clear evidence lists with your banking partners.
- Implement wallet attestation and Travel Rule integration; block deposits from non-compliant counterparties.
- Classify your role under CARF; gap-assess KYC data against CARF attributes (TINs, jurisdictions, controlling persons).
- Design data pipelines: event-level logs for issuances/redemptions and secondary trades; tag tokens with asset identifiers.
- Update privacy notices and customer terms to include CARF reporting.
Hong Kong wants tokenisation to integrate with the real economy. The bar for provenance and tax transparency is rising accordingly.
Useful references
- Policy Statement 2.0 on the Development of Digital Assets in Hong Kong (Government of the HKSAR)
- HKMA Project Ensemble overview
- OECD Crypto-Asset Reporting Framework
- AMLO Schedule 2 CDD and record-keeping (Cap. 615)
If you need a one-page SOW evidence matrix tailored to your specific RWA structure, ask and we’ll share our latest StanCOMP template.


