
HK Compliance 2025: Tokenised Securities & SFC VA Licences

Introduction Hong Kong’s digital asset rules moved fast between 2023 and 2025. If you’re weighing tokenised securities, a virtual asset trading platform (VATP) licence, or stablecoin payments, the key is scoping your activity to the correct regime early—before you spend on tech and onboarding. A few decisions now will save you six months later.
Where Hong Kong stands in 2025
- VATP licensing: The SFC’s regime for centralised VA trading platforms started in June 2023. It requires a licence (Type 1 dealing + Type 7 ATS), fit-and-proper controls, AML/CTF and investor protection measures, with the SFC holding supervisory and intervention powers. As of end-June 2025, 11 VATPs are licensed, up from two at end-January 2024, and retail access is possible for approved platforms. See SFC overview and SFO (Cap. 571).
- OTC and custody proposals: The Government consulted on regulating VA OTC trading and virtual asset custody. Non-compliance under the proposed regimes would attract administrative and criminal sanctions. Expect perimeter clarity and on-chain safeguarding standards to tighten.
- Stablecoins: The Stablecoins Ordinance took effect on 1 August 2025. Issuing fiat-referenced stablecoins in Hong Kong now requires an HKMA licence. See HKMA.
- Payments: Fiat rails remain under the Payment Systems and Stored Value Facilities Ordinance (Cap. 584). If you hold customer fiat or run a multipurpose wallet, you may need an SVF licence or to partner with a licensed SVF/bank.
Tokenised securities: what actually needs a securities licence Tokenisation is technology, not a product category. If the token represents “securities” under the SFO (e.g., shares, bonds, funds), the full securities regime applies—regardless of whether it is on-chain. That typically means:
- Type 1 (dealing in securities) for primary placement or secondary brokerage.
- Type 7 (ATS) to operate a trading venue for security tokens.
- Distribution rules for complex products and PI-only restrictions may apply depending on product features and SFC guidance.
Crucially, the VATP (VA) licence does not cover security tokens. A platform that wants to list both non-security virtual assets and tokenised securities will need to ring-fence activities and comply under both regimes.
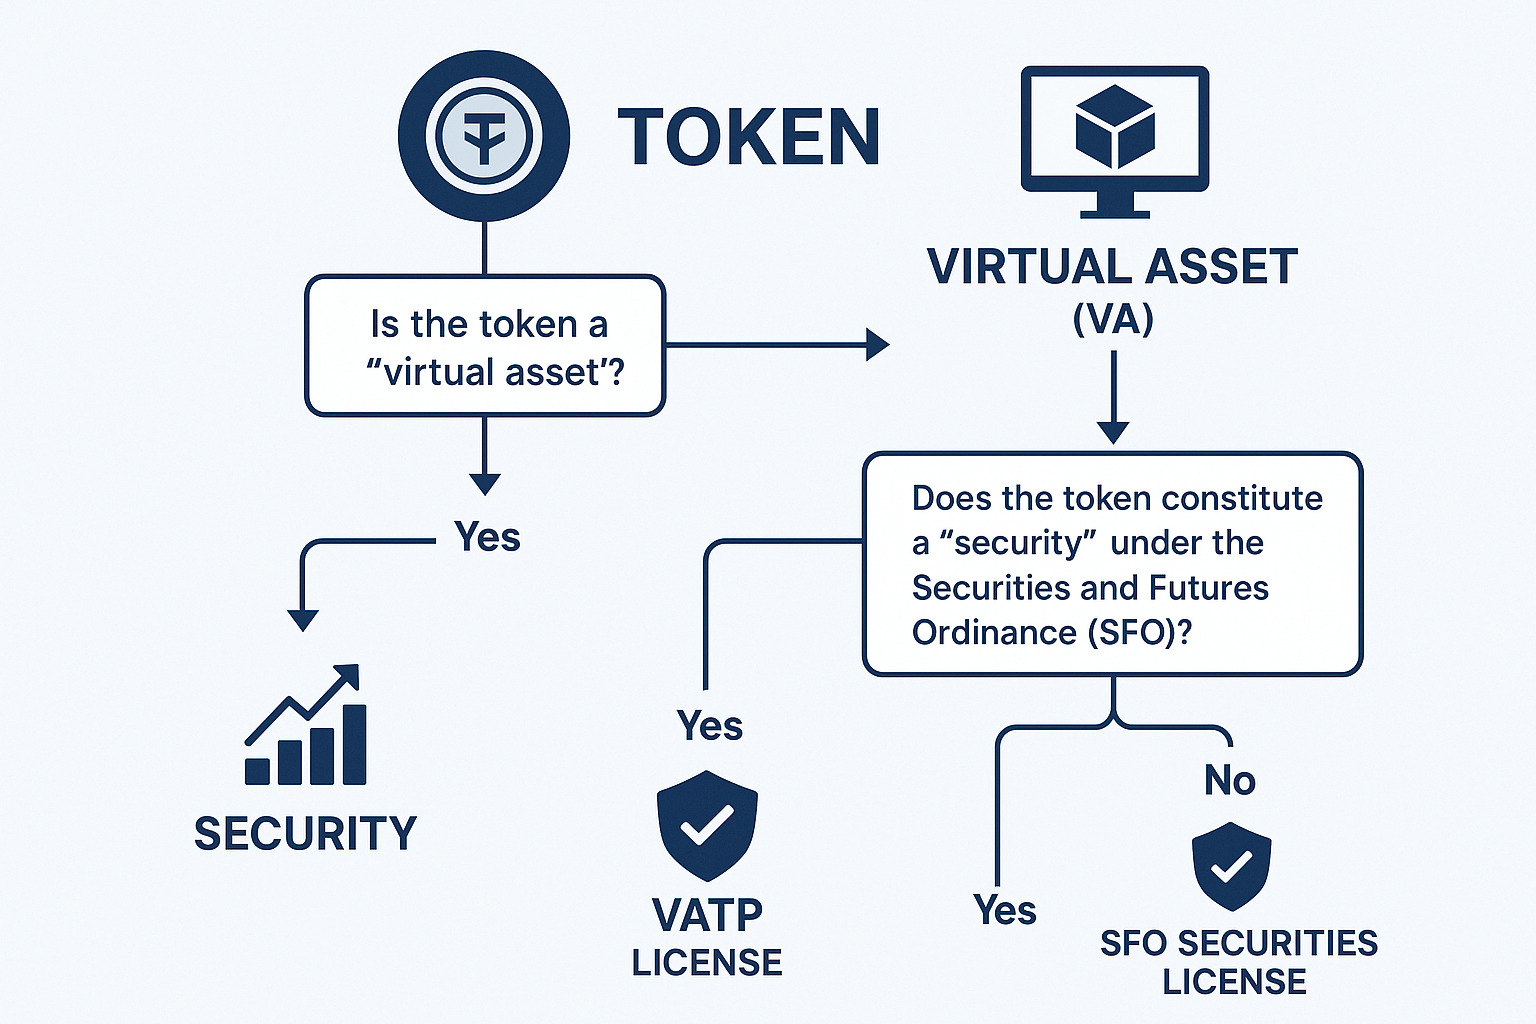
How VATP licensing differs from a securities ATS
- Scope: VATP covers “virtual assets” that are not securities or futures. Securities ATS covers traditional and tokenised “securities.”
- Clients: Retail access is permitted for approved VATPs; security token trading remains more constrained and often PI-only.
- Listing vetting: VATPs follow the SFC’s token admission framework; securities ATS follows prospectus/offering and product rules where applicable.
Payments and settlement: where Cap. 584 bites
- Holding fiat balances linked to VA trading? You either need an SVF licence or to use a licensed SVF/bank with safeguarded float and trust arrangements under Cap. 584.
- Offering stablecoin settlement? If you “issue” a fiat-referenced stablecoin, HKMA licensing now applies. If you only accept a third-party licensed stablecoin as payment, diligence that issuer’s licence and your own AML and sanctions controls.
Practical map of licences and proposals
| Activity | Likely licence/regime | Notes |
|---|---|---|
| Operate centralised VA exchange (non-securities) | SFC VATP (Type 1 + 7) | Fit-and-proper, AML/CTF, investor protection; retail allowed if approved. |
| List/trade tokenised bonds/equities | SFO securities (Type 7 ATS; Type 1 dealing) | Token form doesn’t change “securities” status. |
| OTC dealing in virtual assets | Proposed OTC regime (FSTB/SFC) | Consultation indicates admin/criminal sanctions for breaches. |
| Custody of virtual assets | Proposed custodian regime (SFC) | Supervisory and intervention powers envisaged. |
| Issue fiat-referenced stablecoin | HKMA Stablecoins Ordinance | In force from 1 Aug 2025. |
| Hold client fiat in wallets | Cap. 584 (SVF) | Consider partnering with an SVF/bank. |
What to do now
- Classify your tokens: Map each asset to “VA” vs “security.” Document the legal analysis before product build.
- Pick the right rails: For fiat, use a bank or licensed SVF. For stablecoins, confirm HKMA licensing of the issuer.
- Prepare for OTC/custody rules: Build Travel Rule, segregation, and key-management playbooks now; they’ll be required.
- Plan dual-licensing early if needed: If you want both VA and security tokens, design separate legal entities and control rooms.
Conclusion Hong Kong’s message is clear: you can build here—if you pick the right licence and respect the perimeter. Get the classification right, design custody and payments to today’s standards, and you won’t have to rebuild when the next circular lands. If you need a sanity check on your licensing map, we can review it in under a week with actionable fixes.


